The Florida Keys Luxury Home Buying Timeline: What to Expect Every Step of the Way from Pre-Approval to Moving Day
Understanding the timeline of a Keys luxury waterfront purchase helps you plan, budget, and close with confidence. Here is what happens at each stage.
Key Takeaways
- The full buying timeline from pre-approval to moving day typically spans 60 to 90 days for a financed luxury waterfront purchase, with cash transactions closing in as few as 30 days.
- The due diligence period is the most time-intensive phase and includes seawall and dock inspections, elevation certificate review, wind mitigation analysis, and flood zone verification.
- Working with a buyer's agent who holds contractor and inspector credentials can reduce the timeline by identifying issues during initial property tours rather than during the inspection period.
- Insurance placement is often the longest-lead item in the timeline. Beginning the insurance process during the inspection period rather than at closing prevents delays.
- Planning for post-closing logistics, including utility setup, moving logistics in the island chain, and contractor scheduling for any immediate work, makes for a smooth transition into Keys living.
Buying a luxury waterfront home in the Florida Keys is a rewarding process, but it moves at its own pace. From the first conversation with a lender to the moment you step onto your new dock as the owner, the timeline involves more steps than a typical mainland purchase. Understanding what happens at each stage helps you plan your move, budget your expenses, and avoid surprises that can derail a closing.
Over three decades of guiding buyers through this process, I have worked with hundreds of clients who each brought their own timeline expectations. Some expected to close in two weeks. Others assumed the process would drag on for six months. The reality sits somewhere in between, shaped by the specific requirements of Keys waterfront properties. In this guide, I break down the typical timeline week by week so you know exactly what to expect.
Weeks 1 to 2: Pre-Approval and Team Assembly
The buying process begins before you look at a single property. The first two weeks are about putting your financial and professional team in place so that when the right property appears, you are ready to act.
Secure financing pre-approval. The single most important step is obtaining a pre-approval letter from a lender who understands Florida Keys waterfront properties. Not all lenders know how to evaluate flood zone requirements, wind mitigation discounts, and the total cost of insurance. A pre-approval from a Keys-experienced lender tells sellers you are a serious buyer and gives you the confidence to make an offer quickly. Read my guide on Securing Financing for a Florida Keys Waterfront Home for detailed guidance.
Choose your buyer's agent. The agent you select will directly affect every stage of the process. Look for an agent with deep Keys experience, a successful transaction history, and ideally contractor or inspector credentials. My combination of Sales Associate, Contractor, and Home Inspector licenses means I evaluate seawalls, docks, elevation certificates, and wind mitigation as a standard part of my service, saving you the time and cost of coordinating multiple specialists.
Assemble your advisory team. Beyond your agent and lender, you will need an insurance agent who specializes in Florida coastal properties, a title company with Keys experience, and a marine contractor for any specialized waterfront inspections. The right agent can help you identify these professionals. For a complete guide to building your team, read Assembling Your Dream Team: Who You Need on Your Side When Buying a Florida Keys Waterfront Home.
Weeks 2 to 4: Property Search and Evaluation
With your team in place, the search begins. This phase typically lasts two to three weeks for buyers who know what they want, though some clients spend months exploring the market.
Define your criteria. Before touring properties, clarify what matters most to you. Is deep-water access essential? Do you want open-water views or the protection of a canal? Is year-round living or a seasonal retreat your goal? Each community in the Keys offers a different combination of these factors.
Tour properties with an expert eye. When I tour a property with a client, I look beyond the finishes and the views. I examine the seawall construction, the dock pilings, the age of the roof, the impact windows, and the elevation certificate. I identify red flags early, which saves my clients from falling in love with a property that has hidden issues. Our Complete Florida Keys Waterfront Property Inspection Checklist covers everything that needs to be reviewed.
Narrow your choices. By the end of this phase, you should have one to three properties that meet your criteria. Your agent will prepare comparable market analysis for each to guide your offer strategy. For a deeper look at the communities available, explore our community guides page and the complete buyer's guide.
Weeks 4 to 5: Making the Offer
Once you have identified the right property, the offer phase begins. This typically takes one to two weeks from initial offer to accepted contract.
Determine your offer strategy. The right offer price depends on comparable sales, the condition of the property's waterfront infrastructure, and current market conditions. If my evaluation reveals seawall or dock issues, I help my clients factor those costs into their offer.
Include appropriate contingencies. Your offer should include contingencies for inspection, financing, and insurance. In the Keys, I recommend including contingencies for elevation certificate review and wind mitigation report verification, as these directly affect your long-term ownership costs. For a complete guide to the offer process, read The Complete Guide to Making an Offer on a Florida Keys Waterfront Home.
Negotiate in good faith. The Keys luxury market is relationship-driven. Sellers who connect with serious, well-prepared buyers are more likely to negotiate on price and terms. A pre-approval letter, a knowledgeable agent, and a clean offer go a long way.
Weeks 5 to 8: The Due Diligence and Inspection Period
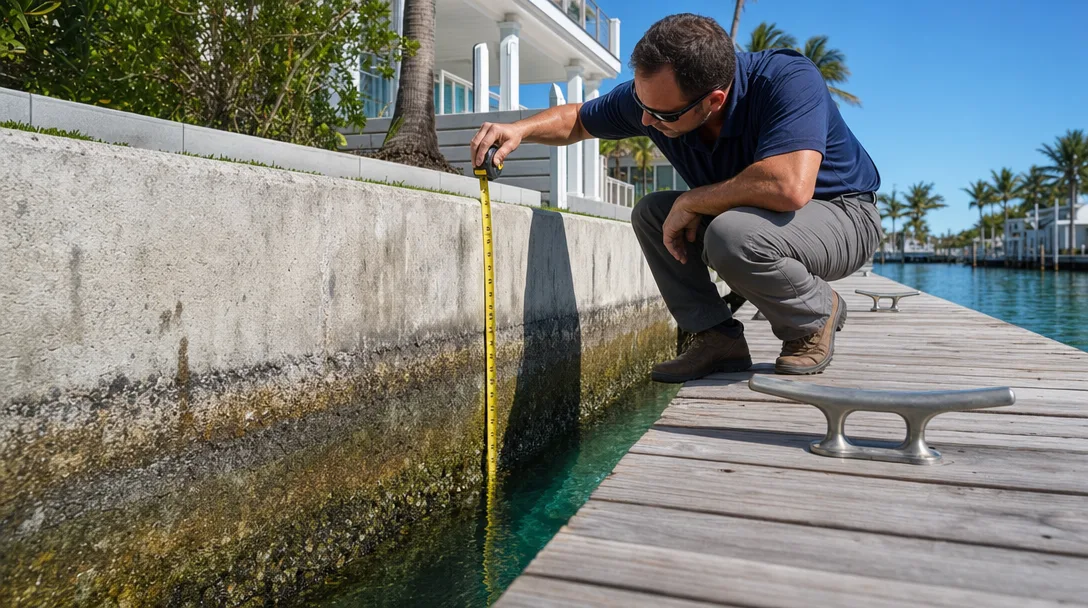
This is the most intensive phase of the buying process. During these three to four weeks, every aspect of the property is evaluated in detail. In the Keys, this phase involves unique steps that go far beyond a standard home inspection.
Seawall and dock inspection. The seawall is the most critical structural element of any waterfront property. A failing seawall can cost $500 to $1,000 or more per linear foot to replace. The dock must be evaluated for structural integrity, electrical safety, and depth at mean low water. As a licensed Contractor, I perform these evaluations as part of my standard service. My Seawall and Dock Inspection Guide covers what every buyer should know.
Elevation certificate review. Every waterfront property has an elevation certificate that documents the relationship between the lowest floor elevation and the base flood elevation. This document determines flood insurance costs. I review elevation certificates as a standard part of my evaluations.
Wind mitigation report review. A wind mitigation report identifies features that qualify for insurance discounts: impact windows, hip roof geometry, secondary water resistance, and shutter systems. A well-documented report can save 30 to 50 percent on windstorm premiums. For a complete walkthrough of these requirements, read Understanding Insurance and Flood Zone Requirements When Buying a Florida Keys Waterfront Home.
General home inspection. A standard home inspection covers HVAC, electrical, plumbing, roof, and structural components. Salt air is hard on mechanical systems, so a thorough inspection is essential, particularly for older properties.
Pest inspection. Termites and wood-destroying organisms are a fact of life in the Keys. A pest inspection is essential for every property.
Weeks 8 to 9: Insurance Placement and Financing Finalization
Insurance is the most complex and time-sensitive aspect of a Keys purchase. This phase typically takes one to two weeks and requires close coordination between your agent, lender, and insurance broker.
Obtain flood insurance quotes. Properties in V (velocity) zones require flood insurance at higher rates than those in A or X zones. Your elevation certificate determines the cost.
Secure windstorm coverage. Windstorm insurance is typically placed through Citizens Property Insurance Corporation or a private carrier. The cost is heavily influenced by the property's wind mitigation features.
Finalize mortgage commitment. Your lender will issue a formal commitment once all documentation is in order. This is the point at which your financing becomes firm, contingent only on the final property appraisal.
Weeks 9 to 10: Title, Survey, and Closing Preparation
The final weeks of the buying process focus on the legal and administrative requirements that lead to closing day.
Title search. The title company will perform a thorough search of public records to verify that the seller has clear title and that there are no liens, encumbrances, or other issues. Your title insurance policy protects against any claims that might arise after closing.
Property survey. A new survey confirms the property boundaries, the location of all improvements, and any encroachments or easements. For waterfront properties, the survey should confirm the bulkhead line and the location of the seawall and dock relative to the property boundary.
Final walk-through. One to three days before closing, you and your agent will walk through the property to confirm that all contracted repairs are complete and that the property is in the expected condition. For a complete guide to the final stages, read Title Search, Survey, and Closing Mechanics for Florida Keys Waterfront Properties.
Week 10: Closing Day
Closing day is the culmination of everything you have worked toward. At closing, you will sign the final documents, transfer the funds, and receive the keys to your new waterfront home.
What happens at closing. Your closing agent will coordinate the signing of the deed, the mortgage documents, and the transfer of funds. You will receive a settlement statement showing all costs associated with the transaction. The deed is recorded with the county, and the keys are handed over.
Post-closing actions. After closing, you will need to set up utilities, register with the local property appraiser, and update your insurance policies. If you are moving from out of state, plan for the logistics of moving your belongings across the Overseas Highway, which can be challenging for large moving trucks. It is also wise to schedule any immediate contractor work, such as seawall repairs or dock upgrades, during the first few weeks of ownership.
A Typical Timeline at a Glance
For a financed purchase, the typical timeline looks like this.
- Weeks 1 to 2: Pre-approval, agent selection, team assembly.
- Weeks 2 to 4: Property search, tours, initial evaluations.
- Weeks 4 to 5: Offer, negotiation, accepted contract.
- Weeks 5 to 8: Due diligence, inspections, elevation certificate review, wind mitigation analysis.
- Weeks 8 to 9: Insurance placement, mortgage commitment.
- Weeks 9 to 10: Title search, survey, final walk-through.
- Week 10: Closing and move-in.
Cash purchases can close in as few as 30 days, as they eliminate the financing timeline. The key variable in every transaction is the quality and completeness of the due diligence, which is where having a contractor-inspector agent makes the most significant difference.
For personalized guidance tailored to your specific timeline and goals, contact Steve Conley for a confidential consultation. I would be honored to guide you through every step of your Keys luxury home purchase.
Steve Conley
Principal, Conley Sales Group at COMPASS the exclusive Compass office in the Florida Keys. Licensed Sales Associate, Contractor, and Home Inspector. Over 30 years and $1.4 billion in career sales serving Key Largo to Key West.
Full BioBuying timeline:
what to know.
How long does it take to buy a luxury waterfront home in the Florida Keys?
A typical financed purchase takes 60 to 90 days from pre-approval to closing. The timeline depends primarily on the complexity of due diligence, including seawall and dock inspections, elevation certificate review, and insurance placement. Cash transactions can close in as few as 30 days. The key to an efficient timeline is having your team assembled and your pre-approval completed before you begin touring properties.
What is the longest part of the buying process?
The due diligence and inspection period is typically the longest phase, taking three to four weeks. This includes the general home inspection, seawall and dock evaluation, elevation certificate review, wind mitigation analysis, and pest inspection. Insurance placement can also create delays if the property's flood zone designation or wind mitigation features require additional documentation. Starting the insurance process during the inspection period rather than waiting until closing prevents last-minute delays.
Can I close faster if I pay cash?
Yes. Cash purchases can close in as few as 30 days, depending on the complexity of the due diligence. Without a mortgage, you eliminate the lender appraisal, underwriting, and commitment process. However, you still need the full inspection and due diligence period, which is where the most valuable insights about your property are discovered. My contractor-inspector background helps accelerate this phase by identifying issues during initial tours rather than during the formal inspection period.
How far in advance should I start the buying process before I want to move?
I recommend starting the process at least three to four months before your desired move date. This allows two to three weeks for pre-approval and team assembly, two to four weeks for the property search, and eight to ten weeks from accepted offer to closing. If you are relocating from out of state or planning a significant renovation before moving in, add additional time for contractor evaluations and permit applications, which can take weeks in the Keys.
What can cause delays in closing?
The most common causes of closing delays in the Florida Keys are insurance placement, particularly for properties in high-risk flood zones or with older wind mitigation features; inspection issues that require additional negotiation or repair work; title issues related to waterfront infrastructure easements; and appraisal gaps in a rapidly appreciating market. Working with a buyer's agent who identifies these issues early dramatically reduces the risk of delays.
Helpful Resources & Related Guides
Deepen your understanding of the Florida Keys buying process with these related resources.
Internal Resources
- How to Buy a Luxury Second Home in the Florida Keys
- Key Largo Luxury Waterfront Community Guide
- Securing Financing for a Florida Keys Waterfront Home
- The Complete Guide to Making an Offer on a Florida Keys Waterfront Home
- Insurance and Flood Zone Requirements for Keys Waterfront Buyers
- Contact Steve Conley for Personalized Buying Guidance
Thinking About Buying or Selling
in the Florida Keys?
Steve Conley brings 30 years of Keys expertise, $1.4 billion in career sales, and contractor-inspector credentials to every transaction. Start with a conversation.
Connect with Steve